yahoo Press
Ray Dalio says the US faces a debt crisis ‘in three years, give or take two.’ 5 things Americans can do now
Images
1 / 4
2 / 4
3 / 4
4 / 4
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.

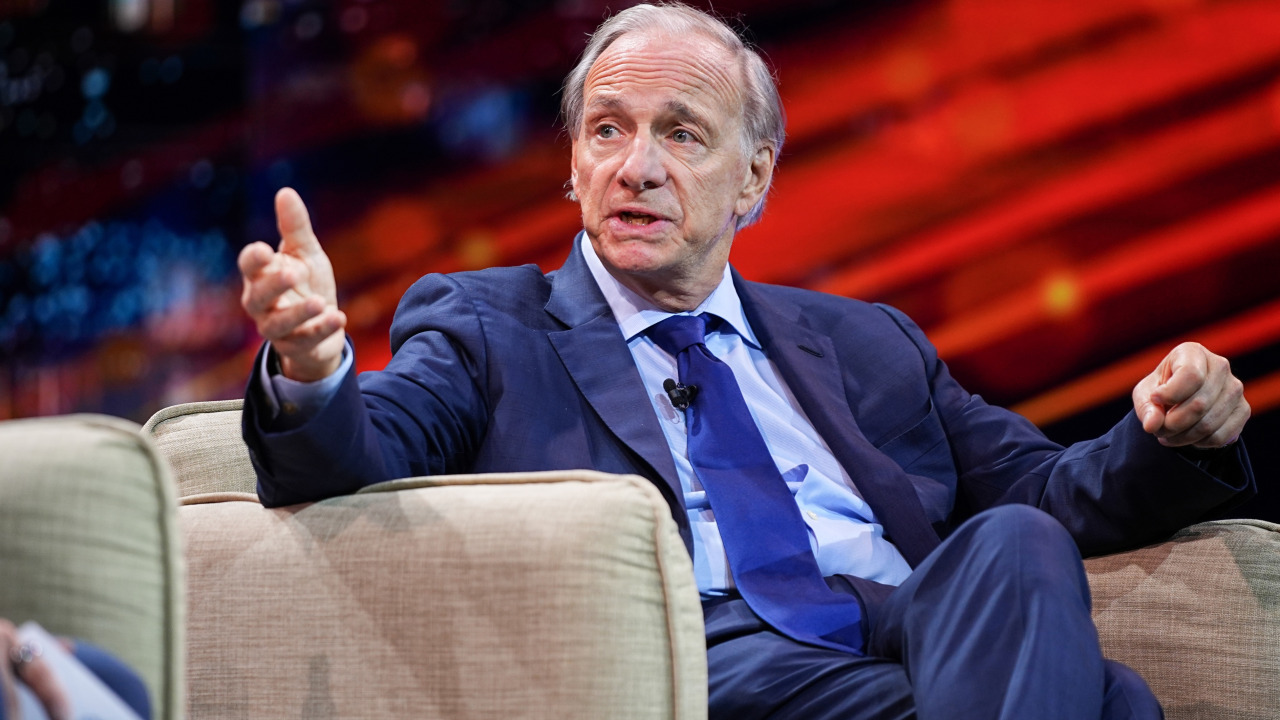
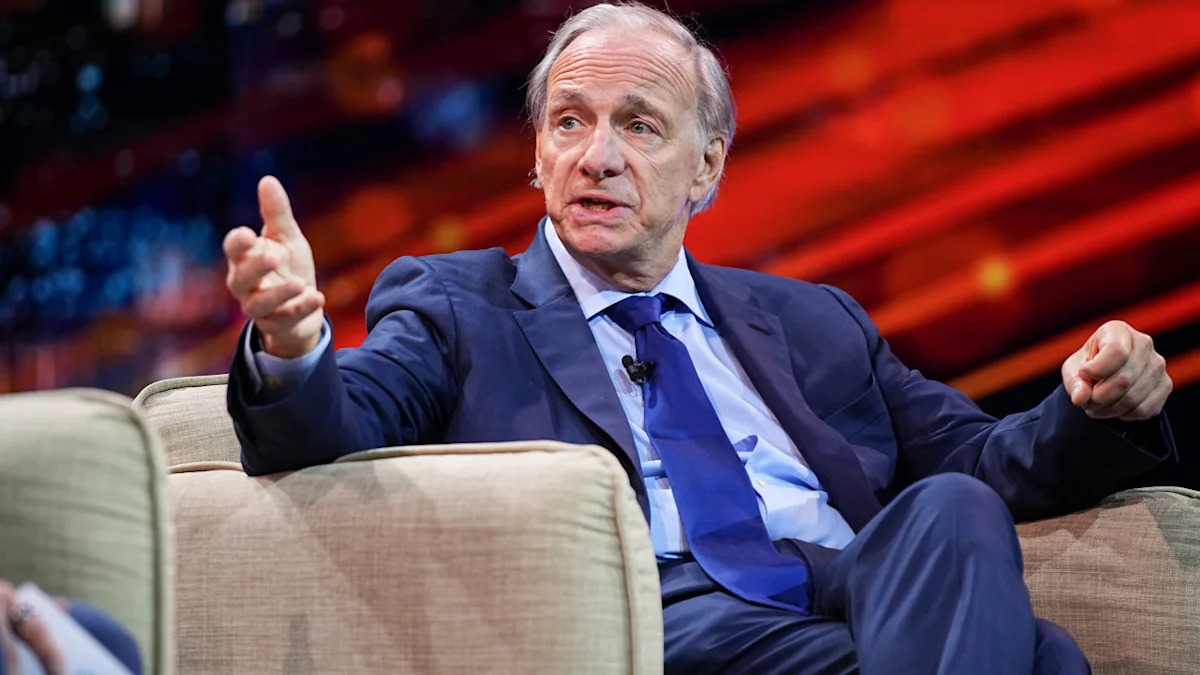
Billionaire Ray Dalio warned last week that the U.S. is heading for a major debt crisis, likening the nation to a person on the verge of a heart attack.

The Bridgewater Associates founder wrote in an August 21 LinkedIn post (1) that a $4 billion U.S. debt buyback (2), combined with rising bond yields (3), a weak dollar and a Japanese sell-off of U.S. bond holdings all point to a potential government debt crisis, which can result in "the equivalent of an economic heart attack that comes when the constriction of debt-financed spending shuts down the normal flow of the economic circulatory system."

Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one

A record 45% of central banks plan to grow gold reserves — and many investors are following suit. Get your free gold IRA guide from Priority Gold

A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change

Dalio wrote that the U.S. will see around a $2 trillion budget shortfall this year, with $11 trillion in debt service payments. Earlier this month the U.S. topped $40 trillion in debt (4) for the first time.

"I am confident that the government's financial condition is at an inflection point because, if this is not dealt with now, the debts will build up to levels where they can't be managed without great trauma," Dalio explained.

Otherwise, he added, the economic heart attack could come at any time, "hastened or postponed by policies and exogenous factors, like big political shifts and wars.

"My guess," he added, "is that it will come in three years, give or take two, if the course we're on is not changed."

The Congressional Budget Office estimates (5) that, for 2026, the deficit will account for about 6% of the U.S. GDP, or $1.9 trillion.

Dalio proposed getting the budget deficit to 3% of the GDP by slashing spending, lowering interest rates and boosting tax revenue — strategies that he says "need to happen concurrently so as to prevent any one from being too large" and causing a "traumatic" adjustment.

He cautioned, though, that "good fundamental adjustments" rather than a forced approach, like the Fed pushing interest rates down "unnaturally," are key.

Treasury Secretary Scott Bessent, however, claimed (6) that the U.S. budget deficit has peaked under President Trump and that "We can grow our way out" of the $40 trillion debt.

And in July, the Federal Reserve called (7) the U.S. financial system "sound and resilient."

But that doesn't mean Dalio is the billionaire who cried wolf.

Government estimates (8) project the gross federal debt will hit $64 trillion in a decade and that the debt is growing faster than the economy (9) — which the Government Accountability Office said could lead to everything from higher borrowing rates for mortgages and cars to cost of living price hikes coupled with wage stagnation.

Experts also say (10) that rising debt could lead to "higher taxes with no additional services because the taxes will pay the interest on the debt."

All of which means that concerned Americans should start taking steps now to shore up their finances to help blunt the blow of a debt crisis if and when it comes.

Read More: Vanguard reveals what's coming for U.S. stocks — and it could be bad news for this group of investors

To protect your money in a debt crisis, Dalio suggested "diversifying well in asset classes," underweighting bonds and investing in "a bit of Bitcoin" and 10% to 15% in gold.

While Moneywise was unable to reach Dalio for comment, certified financial planners Odaro Aisueni and Don Grant offered tips to help prepare your finances for a potential debt crisis:

1. Build and maintain a financial cushion

"Your emergency fund is your first line of defense during financial uncertainty," Aisueni told Moneywise. Grant added that a slush fund for "non-critical lifestyle spending" could also help you avoid using credit for extra expenses.

Grant also believed that retirees might consider setting aside 18 months of living expenses in liquid cash equivalents, which "should be enough to weather a market storm/debt crisis." He also said that if you have a significant estate, you could consider dispersing parts of it to heirs while you're still alive — which could include putting conditions on any gift "by asking [heirs] to use it as a cushion or slush fund" for themselves.

There's another benefit to having money tucked away that doesn't show up on a monthly bank statement — peace of mind. According to research from Vanguard, people with at least $2,000 in emergency savings saw a 21% increase in financial well-being (11). And building that reserve to another three to six months of expenses was associated with an additional 13% increase.

That can be especially valuable during periods of economic uncertainty, when layoffs, market swings or rising costs can make an already-tight budget feel even tighter. Having cash on hand means you're less likely to immediately turn to credit when something unexpected happens.

Still, building the fund is only half the equation. You also want to make sure your cash isn't sitting completely idle. With inflation running at 3.4% in July (12), keeping too much money in a low-interest checking or savings account could mean losing your purchasing power over time.

A high-yield account like a Wealthfront Cash Account can be a great place to grow your uninvested cash, offering both competitive interest rates and easy access to your money when you need it.

A Wealthfront Cash Account currently offers a base APY of 3.30% through program banks, and new clients can get an extra 0.75% boost during their first three months on up to $150,000 for a total variable APY of 4.05%.

That's ten times the national deposit savings rate, according to the FDIC's August report.

Additionally, Wealthfront is offering new clients who enable direct deposit ($1,000/mo minimum) to their Cash Account and open and fund a new investment account an additional 0.25% APY increase with no expiration date or balance limit, meaning your APY could be as high as 4.30%.

With no minimum balances or account fees, as well as 24/7 withdrawals and free domestic wire transfers, your funds remain accessible at all times. Plus, you get access to up to $8M FDIC Insurance eligibility through program banks.

2. Pay down debt

Grant told Moneywise that paying down debt and working to "clean up your credit" puts you "in the best possible position to borrow if necessary." He also said not to take on any "unnecessarily large obligations" like car payments — an especially important note if borrowing and loan costs skyrocket.

That advice becomes particularly important if you're carrying high-interest debt. Credit card balances can become increasingly difficult to manage when interest keeps compounding, so getting those under control can be one of the most effective ways to strengthen your financial position.

Two of the most common strategies for paying down debt are the avalanche and snowball methods. The avalanche method focuses on eliminating your largest debt first, then paying down the others one after the other in a cascade. The snowball technique takes the opposite approach, knocking off smaller debts on your way to the big one.

Another option is to consolidate several debts into a personal loan, preferably with a lower interest rate. You could roll multiple balances into a single loan, giving you one predictable monthly payment and potentially reducing the amount of interest you pay over time. If you're struggling with the logistics of making your payments, this might be the right move for you.

Platforms like Credible can help you compare personal loan options.

You can comparison-shop for the lowest interest rates through Credible's online marketplace with just a few clicks.

You can find personal loans starting at 5.96% APR. Credible also offers a best rate guarantee — and if you close with a better rate than you prequalify for on the platform, you'll get a $200 gift card.

In less than three minutes, you'll see all the lenders willing to help pay off your credit cards or other debts with a single personal loan.

3. Review your financials

Aisueni said that "the goal isn't to reposition your portfolio in anticipation of a downturn" but, rather, to ensure it still aligns "with your risk tolerance, goals and time horizon … so you can remain invested even when markets become volatile or uncomfortable."

Grant also suggested a "monthly budget triage" to eliminate unneeded subscriptions or other expenses that frees up extra cash.

But you don't necessarily have to figure all of this out on your own.

A financial advisor can help you take a step back, assess where your money is going, and build a strategy that accounts for both today's economic uncertainty and your longer-term goals.

And there could be a financial benefit to getting that guidance. Envestnet research found that investors who work with a financial advisor saw 3% higher returns on average than those who didn't (13). While no advisor can guarantee a particular return, professional guidance may help you avoid costly mistakes and stay focused on the bigger picture.

That's where platforms like Advisor.com come in.

You can easily connect with a vetted FINRA/SEC-registered advisor near you for free through Advisor.com.

Here's how it works: Simply enter a few details about your finances and goals, and Advisor.com will comb through its roster and connect you with a qualified expert best-suited for your needs based on your unique financial goals and preferences.

The platform does the heavy lifting for you, vetting advisors based on track record, client ratios and regulatory background. Plus, their network comprises fiduciaries, who are legally required to act in your best interests.

Finding the right advisor isn't always easy — there's no one-size-fits-all solution. That's why Advisor.com lets you set up a free initial consultation, with no obligation to hire, to see if they're the right fit for you.

Building a financial cushion, paying down debt and keeping your portfolio aligned with your goals can all help strengthen your finances. But diversification can play another crucial role, particularly if you're worried about being too heavily exposed to the U.S. stock market.

Alternative assets can give investors exposure to investments that don't necessarily move in lockstep with traditional stocks and bonds.

That doesn't make them risk-free, but they may provide another source of diversification when markets become choppy.

Gold, in particular, has long been viewed as a potential hedge during periods of economic and geopolitical uncertainty. Dalio has previously argued that investors should consider keeping a portion of their portfolio in the precious metal.

"If you look at it just from a strategic asset allocation perspective, you would probably have something like 15% of your portfolio in gold … because it is one asset that does very well when the typical parts of the portfolio go down," he claimed in an interview with CNBC last year (14).

Gold's appeal comes from its long history as a store of value. It isn't tied to the fortunes of one company or dependent on the earnings of a particular industry. And because its supply is limited, it can't simply be created in the same way governments can issue more currency.

That's why gold often attracts investors when inflation, geopolitical tensions, or financial-market uncertainty start heating up. Gold prices have more than doubled over the past five years, hitting multiple records along the way and outperforming the S&P 500 over the same period.

Opening a gold IRA with the help of Goldco allows you to invest in gold and other precious metals in physical forms while also providing the significant tax advantages of an IRA.

With a minimum purchase of $10,000, Goldco offers free shipping and access to a library of retirement resources. Plus, the company will match up to 10% of qualified purchases in free silver.

If you're curious whether this is the right investment to diversify your portfolio, you can download your free gold and silver information guide today.

For investors willing to take on considerably more risk, cryptocurrency is another asset class worth knowing about. Bitcoin, in particular, has increasingly gained momentum as a potential hedge against the U.S. dollar.

Recent bond purchases announced by Treasury Secretary Scott Bessent have resulted in the rise of the debasement trade — an investment strategy in which investors move some of their money away from traditional government-backed currencies and toward hard assets that may better preserve purchasing power (15).

Bitcoin surged nearly 22% following Bessent's announcement of Treasury buybacks, marking its biggest three-day rally since 2023 (16).

If you're looking to diversify beyond traditional stocks and ETFs, Robinhood Crypto lets you buy and sell cryptocurrencies with as little as $1.

With some of the lowest trading costs on average in the U.S., you could end up with up to 2.7% more crypto compared to other platforms.

Robinhood Crypto makes it easy to make investing a habit with recurring buys on a fixed schedule, while giving you access to all your favorite coins — from Bitcoin and Ethereum to Solana, Dogecoin, XRP, and more.

You can also transfer crypto securely to other wallets, set custom price alerts, track market trends, and manage your portfolio all in one place.

Robinhood ensures the security of your cryptocurrency is a top priority, with the majority of coins held in offline cold storage. Robinhood also carries crime insurance against theft and cyber breaches, and 24/7 customer support is available if you need help.

Ultimately, experts have warned of a debt crisis for years and no one, including Dalio, knows if it will actually hit.

But by taking steps to protect your pocketbook, you could find yourself in a better financial position regardless of if the crisis ever materializes.

— With files from Mike Crisolago

The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes

Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP

Millionaires under 43 hold only 32% of their wealth in stocks. Here's where their money is actually going

Dave Ramsey says this 1 indulgent purchase stops Americans from becoming wealthy. Here's what he recommends instead

Get Warren Buffett's best investing lessons, free. Join 250,000 readers getting Moneywise's sharpest money reporting every week. Subscribe and we'll send you our guide to the ideas that built Buffett's fortune as a welcome gift.

We rely only on vetted sources and credible third-party reporting. For details, see our editorial ethics and guidelines.

LinkedIn (1); CNBC (2), (6),(12),(14),(16) ; PBS (3); The Wall Street Journal (4); Congressional Budget Office (5); Federal Reserve (7); Congressional Budget Office (8); U.S. Government Accountability Office (9); Yahoo Finance (10); Vanguard (11); Envestnet (13); Citigroup (15)

This article provides information only and should not be construed as advice. It is provided without warranty of any kind.
Comments
You must be logged in to comment.