yahoo Press
Time to Buy: Wall Street Says Dell Stock Could Climb 38% in a Year
Images
1 / 4

2 / 4
3 / 4
4 / 4
The above button links to Coinbase. Yahoo Finance is not a broker-dealer or investment adviser and does not offer securities or cryptocurrencies for sale or facilitate trading. Coinbase pays us for certain activity generated through this link. Prices displayed are informational.

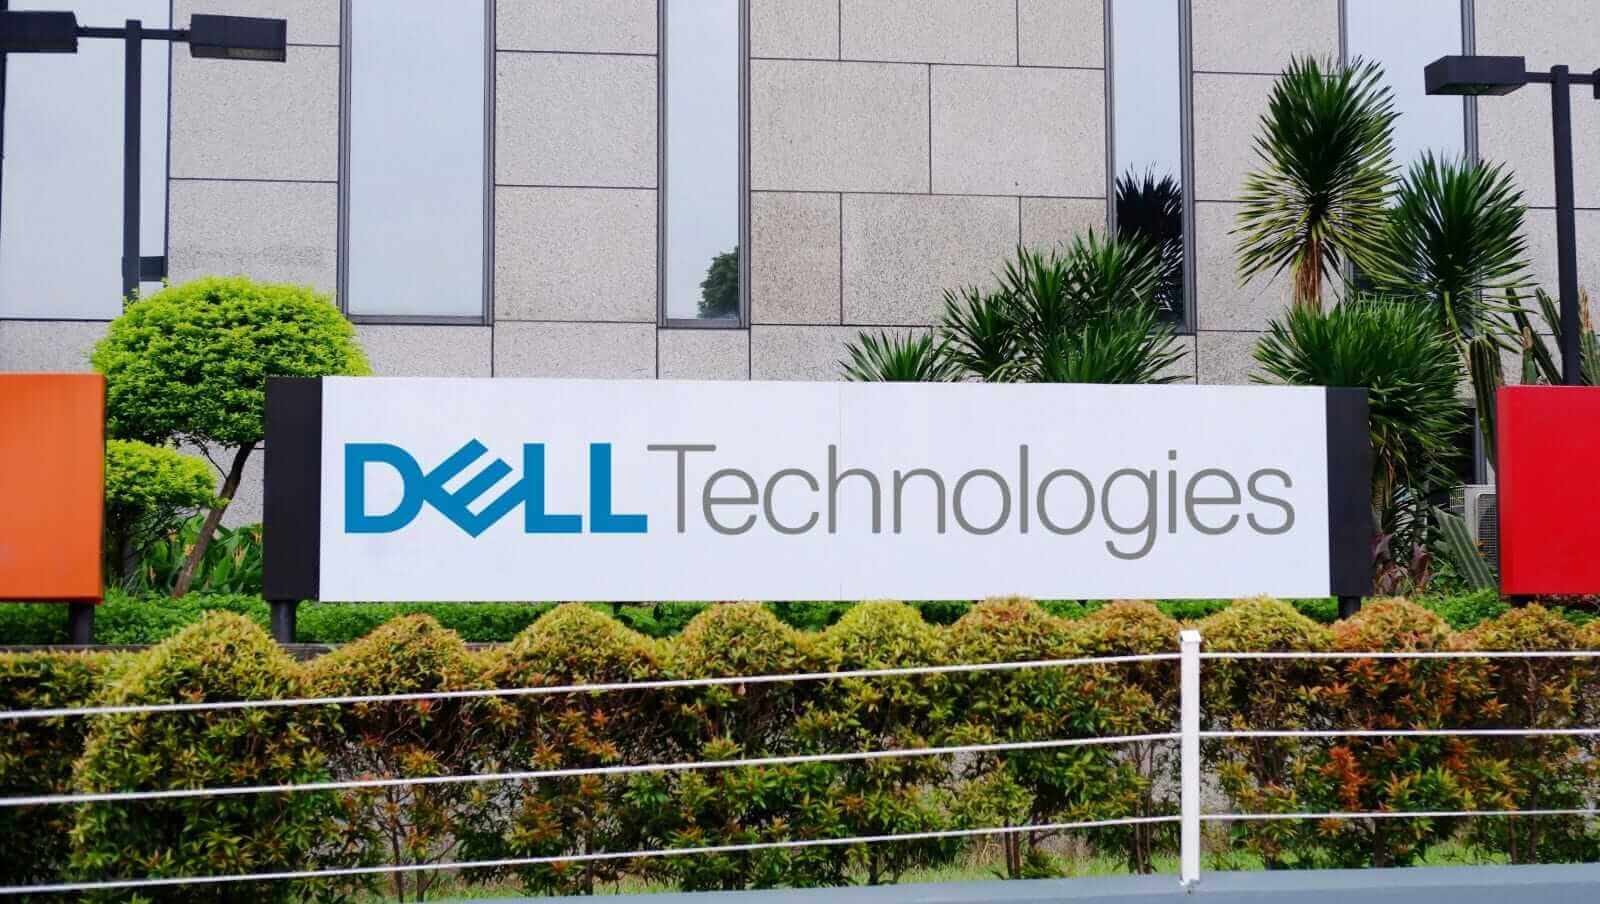
Dell Technologies (DELL) shares have surged more than 316% so far in 2026, fueled by robust demand for AI infrastructure, increased enterprise investment in modernizing IT systems, and continued expansion of its customer base.

The company is also benefiting from strong demand for its AI-optimized servers, and the momentum is likely sustainable in the coming quarters. At the same time, rising AI demand is also driving demand for traditional servers and networking equipment, further strengthening Dell's long-term growth prospects.

'Not Tens Of Billions, But Tens Of Trillions': Nvidia CEO Jensen Huang Says AI Is Like the New Electricity and the Scale Is Unlike Any Tech in History

What It Means for MSFT Stock Investors as Microsoft Switches to 2 Business Segments

RKLB Stock Jumps as Rocket Lab Debuts New Solar Cell for Space

Markets move fast. Keep up by reading our FREE midday Barchart Brief newsletter for exclusive charts, analysis, and headlines.

With a favorable demand backdrop, Wall Street analysts remain optimistic about Dell stock. The highest current price target for Dell stock is $735 per share, implying about 38% upside from the Sept. 8 closing price of $533.88.

Dell's growth trajectory remains strong as accelerating investment in AI infrastructure drives demand across its broader portfolio. The company reported record second-quarter revenue of $47 billion, up 58% year-over-year, while earnings per share (EPS) rose 203% to $7.04. The results highlight AI remains Dell's primary catalyst. The tech giant has secured more than $130 billion in AI server orders over the past 12 months, including a record $60.9 billion in orders during the last reported quarter.

Importantly, Dell's opportunity pipeline is also expanding beyond AI-optimized servers. The expansion of AI workloads is increasing demand for compute, networking, and storage infrastructure. At the same time, the broader modernization cycle is helping traditional server and networking demand accelerate alongside AI investment.

The company is also seeing improving trends in other businesses. Storage has returned to growth, supported by demand for Dell's internally developed storage products, while Client Solutions Group (CSG) revenue is growing at its fastest pace in five years.

The momentum could strengthen ahead. For the third quarter, Dell expects revenue of approximately $49 billion at the midpoint, implying year-over-year growth of 80%. Infrastructure Solutions Group (ISG) revenue is expected to increase about 145%, supported by approximately $19 billion of AI server revenue.

For the full year, Dell raised its revenue guidance by $25 billion to $192 billion at the midpoint, representing 70% growth. Adjusted EPS is expected to reach $25.50, an increase of approximately 150%. ISG revenue is projected to grow about 120%, with AI server revenue expected to triple year-over-year to $74 billion. Traditional server revenue is expected to more than double, while storage and CSG revenue are projected to increase in the mid-teens.

Overall, Dell's outlook remains solid, driven by surging AI infrastructure demand and improving performance across its broader portfolio. With record AI server orders, stronger storage and CSG growth, and strong revenue and earnings guidance, the company is well positioned to benefit from the continued expansion of AI and enterprise infrastructure spending.

Dell stock has rallied significantly. However, its valuation doesn't look stretched at current levels, which leaves room for shares to move higher. The stock is trading at 24.6 times forward earnings, but that appears reasonable given the strong EPS growth expected in 2026 and beyond.

Analysts expect Dell's EPS to jump 171.8% in 2026. Moreover, its bottom line is projected to grow by about 12.9% in 2027. The earnings outlook for 2027 could prove conservative. Robust demand, an increasing contribution from Dell's proprietary intellectual property, and disciplined execution on both operating costs and pricing are strengthening the company's earnings profile. With these factors continuing to support margins, analysts will likely raise their estimates further.

Dell's record AI server orders, accelerating enterprise infrastructure spending, and improving performance across storage and client solutions are giving Dell multiple growth engines. At the same time, its reasonable valuation leaves room for further upside. Together, these factors suggest the $735 price target is achievable.

Analysts remain optimistic, with Dell stock carrying a "Strong Buy" consensus rating.

On the date of publication, Sneha Nahata did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. This article was originally published on Barchart.com
Comments
You must be logged in to comment.