yahoo Press
Does renters insurance cover fire?
Images
1 / 11
2 / 11
3 / 11

4 / 11
5 / 11
6 / 11
7 / 11
8 / 11
9 / 11
10 / 11
11 / 11
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.

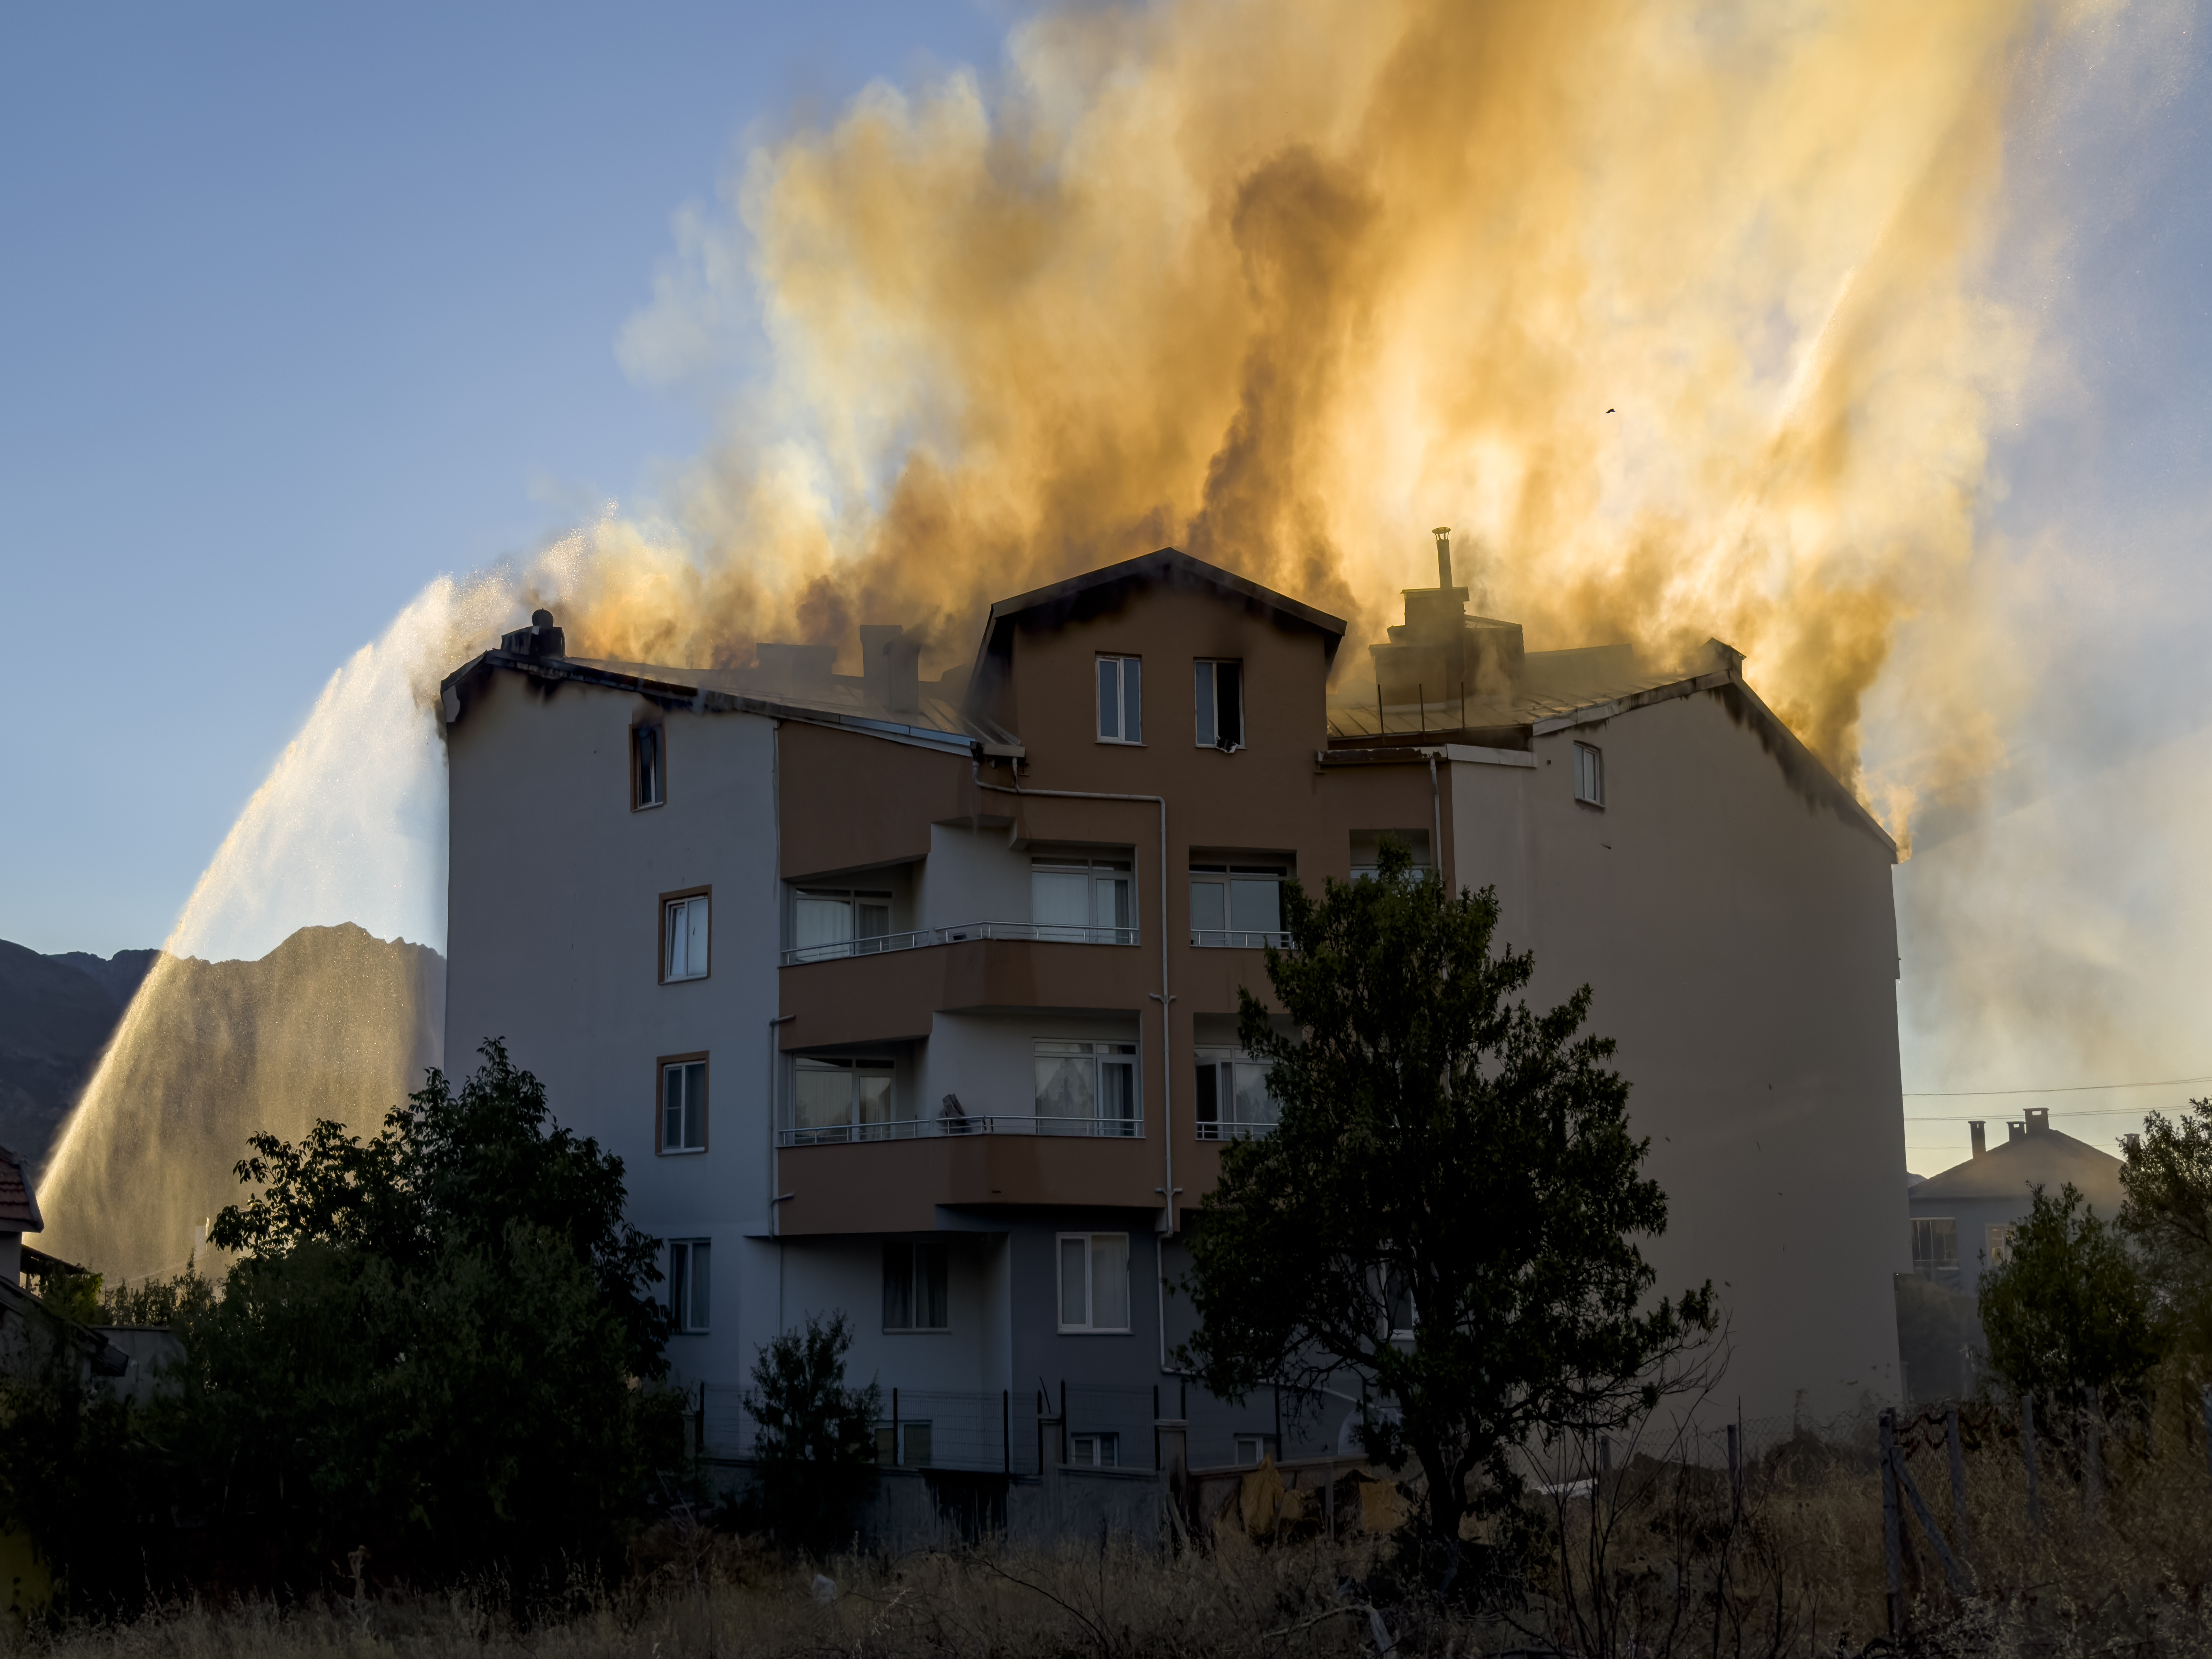
If there's a fire in your apartment, renters insurance can help replace any damaged items. It may also help pay for smoke-damaged items, temporary hotel stays, and certain expenses if you can't live in your rental while it's being repaired.

The biggest thing to know is that renters insurance covers your stuff, but not the building itself. So your couch, clothes, laptop, mattress, and dishes may fall under your policy, but the walls, floors, roof, and built-in appliances likely fall under your landlord's insurance.

Depending on your policy, fire damage may trigger several different parts of your renters insurance coverage at the same time.

Personal property coverage helps pay to repair or replace any items you own that were damaged as a result of a covered fire.

This could include:

Furniture

Clothing

Electronics

Kitchen items

Books

Bedding

Sports equipment

Small appliances, like microwaves and air fryers

Smoke can ruin your furniture, clothing, electronics, artwork, and other possessions, just like an actual fire. And in many cases, your renters insurance treats smoke damage similarly to fire damage.

If a kitchen fire occurs elsewhere in the building and thick smoke seeps into your apartment, your policy may help cover the cost of damaged items, even if your unit never actually catches fire.

Additional living expenses (ALE) coverage is also known as loss-of-use coverage. Depending on the specifics of your policy, it can help pay for any of these expenses if you can't stay in your apartment while it's being repaired:

Hotel stays

Temporary rental housing

Restaurant meals

Laundry costs

Pet boarding

Other reasonable expenses

ALE coverage is usually 20% of your personal property amount. So if you have $20,000 in personal property coverage, ALE coverage could be capped at $4,000.

Liability coverage could apply if you're responsible for any of the fire damage. For instance, if you leave a candle burning and it starts a fire that damages neighboring apartments, liability coverage could help pay for damage to other people's property, medical bills, and even legal expenses if you're sued.

You're usually required to buy at least $100,000 in liability coverage, although your landlord may have different minimum limits. You may also want more liability coverage if your net worth exceeds $100,000. (Ideally, you want enough coverage to protect your assets.)

Renters insurance can cover a lot after a fire, but it won't cover these items:

Damage to the building itself: Your landlord's insurance policy would typically handle any structural damage to your unit, like the roof, drywall, flooring, cabinets, and more.

Your deductible: Just like with any insurance policy, you're responsible for paying your deductible yourself. Generally, if you have a smaller claim that's around the same amount as your deductible, it may not be worth filing a claim.

Intentional fires: If you deliberately start a fire or intentionally damage your own property, your claim will almost certainly be denied.

Certain high-value items: Many renters insurance policies place a cap on how much they'll pay for expensive items like a diamond ring, a watch collection, an art collection, firearms, and cash. If you have any of these items, you may need to add a rider for scheduled property coverage to insure them for the full amount.

Losses that exceed your coverage limits: Every renters insurance policy has caps on what it'll pay out. Once you hit this limit, you're usually responsible for the difference. If your limits feel too low, talk to your insurance provider about purchasing more coverage. You don't want to lose all your belongings in a fire, just to find out you were underinsured.

Renters insurance typically covers many types of damage caused by accidental fires.

Scenario

Typically covered?

Why

You accidentally start a kitchen fire while cooking

Yes

Accidental fires are generally covered

A faulty appliance catches fire

Yes

Mechanical failures and accidental fires are usually covered

An electrical fire starts inside the walls

Yes

Electrical fires are a common covered peril

A neighbor's apartment catches fire and damages your belongings

Yes

Your policy may cover damage to your personal property

A wildfire damages your rental and belongings

Usually

Wildfire damage is generally covered under standard renters policies

Lightning strikes the building and causes a fire

Yes

Lightning is a common covered peril

Smoke from a fire damages your belongings

Usually

Smoke damage is often covered the same way fire damage is

An arsonist sets fire to the building

Usually

Criminal acts by a third party are generally covered

You intentionally start the fire

No

Intentional acts are excluded

A fire happens before you purchase coverage

No

Insurance doesn't cover losses that occurred before the policy was active

Renters insurance policies typically settle claims on an actual cash value (ACV) or replacement cost value (RCV) basis. Whichever one your policy pays will have a big influence on how big your claims payout will be.

Settlement type

What it means

Actual cash value (ACV)

Pays the item's current value after depreciation

Replacement cost value (RCV)

Pays what it costs to buy a comparable new item today

Here's an example to highlight the difference between ACV and RCV:

Say a fire destroys your five-year-old television, which you originally paid $1,000 for. Under an ACV policy, the insurance company may pay you $400 or $500 based on the TV's age and wear. But under an RCV policy, you may receive closer to $1,000 or what it would cost to buy a similar new television today.

Not sure which type of coverage you have? Check your declarations page or call your insurance company. It's much better to find out before a fire than after one.

If you've just experienced a fire, your first priority is safety. After that, you can follow these steps to begin the claims process.

It's tempting to start cleaning everything up immediately. But before you do, take as many photos and videos as possible. Try to capture any and all damage, as well as the overall condition of the apartment. No amount of documentation is too much at this stage.

Your insurance company will most likely ask for a loss inventory to verify what's damaged or destroyed. Go ahead and start this inventory list before you file a claim.

As you make note of your items, try to include as many details as possible, like:

Item description

Brand and model number

Approximate purchase date

Original purchase price

Estimated replacement cost

You can look at digital receipts, purchase histories, credit card statements, and bank statements if you need help figuring out when you bought something or how much you paid for it.

Even if it appears that only your belongings were affected by the fire, there could be hidden damage inside the walls, ceilings, or electrical systems. Let your landlord know so they can file a claim with their own insurance if needed.

You can typically file a renters insurance claim for fire damage online, through your insurance company's mobile app, or by calling customer service.

When you file, you'll most likely be asked for this information:

When the fire occurred

What happened

What property was damaged

Whether the apartment is still livable

Remember loss of use coverage? If you need to stay in a hotel, eat restaurant meals, pay for boarding your pet, or do laundry at a laundromat after a fire, keep every receipt. These costs may be reimbursable.

Your insurance company may assign an adjuster to review the fire damage and verify your losses. Respond as quickly as you can to any follow-up questions they have or documentation they need to get your claim fully processed.

Every situation is different, but they could ask for:

Additional photos

Receipts

Proof of ownership

A detailed inventory of damaged items

Before you accept a claim payout for fire damage, review the settlement for any errors.

Pay close attention to:

Your deductible

Coverage limits

Any depreciation applied

Whether your policy pays actual cash value or replacement cost

If something doesn't look right, ask questions. It's much easier to address concerns during the claims process than after the claim has been closed.

A fire is a terrible time to discover that you don't have enough renters insurance. A few simple steps can make a huge difference if you ever need to file a claim:

Create a home inventory. Take photos or videos of each room and save them to the cloud. (This can also help you estimate how much coverage you need.)

Keep receipts for expensive purchases. This makes it much easier to prove ownership and value.

Review your personal property limits annually. Make sure your coverage still reflects what you actually own.

Consider replacement cost coverage. It generally provides a larger payout than actual cash value coverage after a loss.

Add on coverage for valuable items. Expensive jewelry, antiques, electronics, and other collectibles may have lower coverage limits than you realize.

Store important documents digitally. You can much more easily access insurance information, receipts, and inventories after a disaster if you back them up online.

Renters insurance will typically cover damage that results from a neighbor accidentally starting a fire. Your policy may also help pay for temporary housing if you can't live in your apartment. You would generally file a claim through your own insurance company first, even if someone else caused the fire.

If you accidentally start a kitchen fire or leave a candle burning, your policy may help cover damage to your belongings through your personal property coverage, as well as damage to anyone else's belongings through your liability coverage.

Renters insurance often covers smoke damage even if flames never reach your apartment. For example, if a fire in another unit fills your apartment with smoke and damages your furniture, clothing, or electronics, your renters insurance can help pay to repair or replace those items.

If you can't live in your apartment after a covered fire, the loss-of-use part of your policy (also known as ALE coverage) can help pay for a hotel, temporary housing, meals, and other expenses. Check your policy for coverage limits and details.

Damage from wildfires is typically covered by renters insurance. If you're in California, Colorado, Oregon, or another area prone to wildfires, review your personal property limits and make sure they're high enough to replace everything you own after a major loss. In California, for example, people often realize they are underinsured after a disaster has already struck.

Renters insurance typically covers personal belongings, liability, and additional living expenses. Here's what you need to know about typical coverage and add-ons.

Renters insurance protects you and your personal belongings when renting a property. Here's everything you need to know about coverage, cost, and how to get it.

Does renters insurance cover theft? Learn what's covered, common exclusions, and how to file a theft claim.

Most homeowners insurance policies include wildfire insurance, but wildfire damage may be excluded in high-risk areas. Here’s everything you need to know.

Does renters insurance cover water damage? Learn when renters insurance covers water damage, flooding, sewer backups, and more.

Learn how to file a renters insurance claim step by step, including what documents you'll need, how long claims take, and what to do if a claim is denied.
Comments
You must be logged in to comment.