yahoo Press
Nearly half of retirees leave work earlier than planned — the 3 reasons Americans are retiring at 62 instead of 65
Images
1 / 4
2 / 4
3 / 4
4 / 4
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.

Most American workers assume they'll call it quits around 65. But most are wrong, and the gap between expectation and reality carries serious financial consequences.

According to the 2026 Retirement Confidence Survey put out by the Employee Benefit Research Institute (EBRI) and Greenwald Research, nearly half of retirees (46%) left the workforce earlier than planned (1). The average actual retirement age was 62, while the average age workers expected to retire remained 65.

Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one

JPMorgan still sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Learn more with a free guide from Priority Gold

The tax breaks in Trump's 'big beautiful bill' expire after 2028 — and experts say most people won't act in time. What to do before the window closes

A separate study paints an equally striking picture. The Society of Actuaries Research Institute (SARI)'s latest Retirement Risk Survey — which surveyed 2,012 Americans aged 45 to 80 — found that 59% of retirees left the workforce before they had expected, while only 6% retired later than planned (2).

What's driving those early exits?

Three causes dominate the data — and two of them have nothing to do with personal choice. Here are the top three reasons why Americans are retiring early.

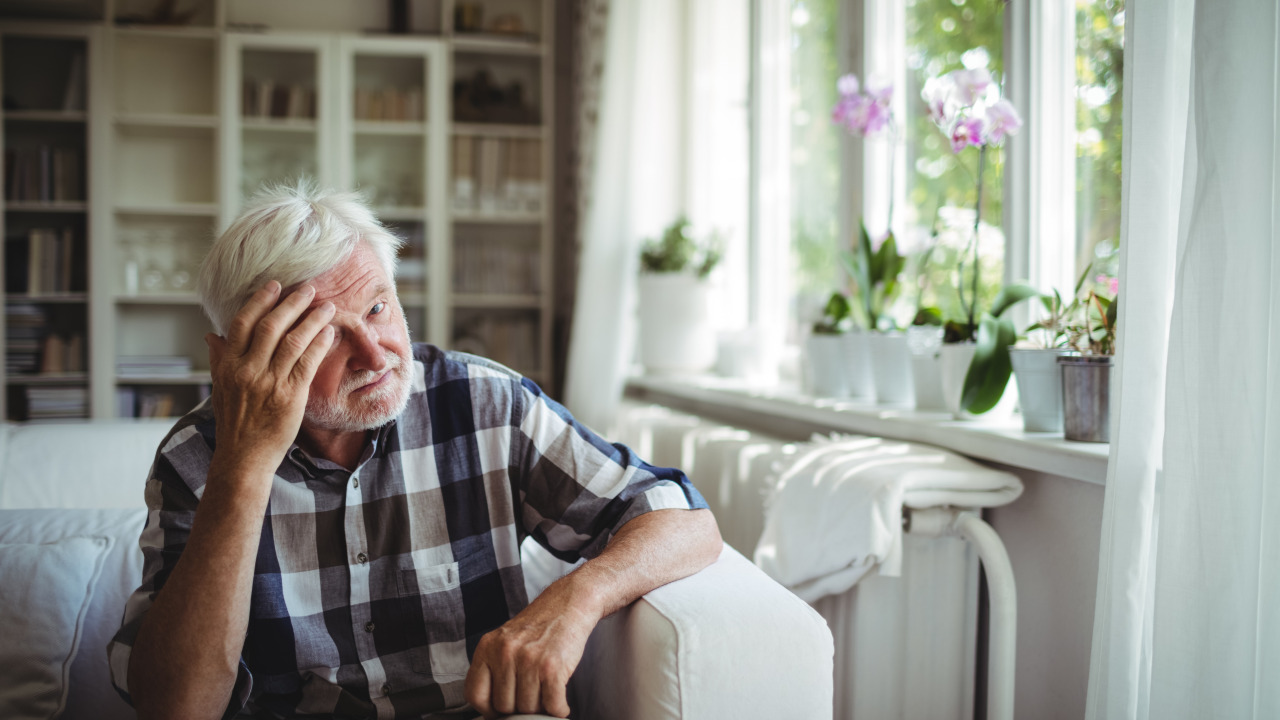
Health problems are the single most common cause of unplanned early retirement, and they fall hardest on lower-income workers. According to the SARI report, changes in health status were cited by 49% of retirees with incomes under $35,000 as the primary reason for retiring early (2).

The EBRI/Greenwald survey reinforces this finding, with TheStreet noting that 41% of those who retired early did so because of a health problem or disability — 10% more than the year before (3).

That financial impact compounds quickly. Retiring at age 62 instead of 65 means three fewer years of contributions, three additional years of withdrawals and — critically — three years without employer-sponsored health insurance before Medicare eligibility begins at age 65 (4).

The second major cause of early retirement isn't voluntary either. Corporate restructuring, downsizing and business closures accounted for 35% of early retirements, according to the EBRI/Greenwald survey. When older workers lose jobs, reemployment at comparable wages is often difficult to achieve — and many effectively retire by default rather than by design (3).

The SARI report (2) confirms job loss as a consistent factor across all income levels, impacting 18% to 20% of early retirees across all household income. It was circumstances like this and health-related events — entirely outside a worker's control — that drove 76% of all unplanned early retirements last year, TheStreet reported (3) based on the EBRI/Greenwald survey.

"Certainly, those are not people doing it because they want to," coauthor of the SARI report Timothy Geddes, a managing director at Deloitte Consulting, told USA Today (5). "They're doing it because they have to."

Read More: Millionaires under 43 hold only 25% of their wealth in stocks. Here's where their money is actually going

For higher-income workers, the picture looks different. The SARI report found that among retirees with incomes over $75,000, job dissatisfaction was the leading reason for early retirement, cited by 29% of respondents — ahead of health status or job loss. Achieving a savings goal earlier than expected ranked second at 24% (2).

For these workers, early retirement is a choice, and sometimes an active one.

"Some of the high-income retirees reported that they achieved their financial goals, so they stopped working," Geddes told USA Today (5). "And that's not in any way negative."

The financial math of early retirement is unforgiving if you're unprepared. As of 2026, the median retirement savings balance for an American in their 50s is $460,363, according to data collected by Empower (6). But $1 million or more is often cited as the "magic number" for retirement (7).

The good news is that the tax code provides specific tools for people in their late 50s and early 60s to accelerate savings. According to the IRS, workers aged 50 and older can contribute an additional $8,000 to a 401(k) above the standard limit in 2026, and workers aged 60 to 63 qualify for an even larger catch-up contribution of $11,250 (8).

"There's a great deal of making adjustments and learning to live with what you have," Craig Copeland, director of wealth benefits research at EBRI, told USA Today (5).

That means for the majority of Americans who won't get to choose exactly when they retire, building flexibility into the plan — rather than betting on working until age 65 — can be the more reliable strategy.

The closer you get to retirement, the less room there is for financial setbacks. Even if your job feels secure today, an unexpected layoff, medical expense or major home repair could throw your retirement timeline off course if you aren't prepared.

That's why experts often say that building a healthy emergency fund should probably be high on every near-retiree's checklist. According to Suze Orman, relying solely on your investment portfolio isn't enough, because markets don't always behave the way investors expect. To avoid selling investments during a downturn, she recommends keeping three to five years of living expenses safely tucked away.

"It's not always that stocks go down and bonds go up, or bonds go down and therefore stocks go up. Sometimes everything can go down," Orman said on the Women & Money podcast (9).

"If you really wanna be on the safe side, it's five years," she added. "If you wanna just play it so that you have at least three years, okay, you can do that, as well. Maybe you split it, and you do four years."

A high-yield account like a Wealthfront Cash Account can be a great place to grow your uninvested cash, offering both competitive interest rates and easy access to your money when you need it.

A Wealthfront Cash Account currently offers a base APY of 3.30% through program banks, and new clients can get an extra 0.75% boost during their first three months on up to $150,000 for a total variable APY of 4.05%.

That's ten times the national deposit savings rate, according to the FDIC's June report.

Additionally, Wealthfront is offering new clients who enable direct deposit ($1,000/mo minimum) to their Cash Account and open and fund a new investment account an additional 0.25% APY increase with no expiration date or balance limit, meaning your APY could be as high as 4.30%.

With no minimum balances or account fees, as well as 24/7 withdrawals and free domestic wire transfers, your funds remain accessible at all times. Plus, you get access to up to $8M FDIC Insurance eligibility through program banks.

A comfortable retirement isn't just about how much you've saved — it's also about getting the most from every source of income available to you.

Social Security's delayed claiming strategy remains one of the most powerful levers available: For each year you delay claiming beyond the age of 62, your monthly benefit grows — reaching its maximum at age 70. Plus, stopping work doesn't require you to claim immediately, and for those who can manage on savings or a spouse's income, delaying benefits by even a few years can significantly increase lifetime income (10).

That said, delaying isn't automatically the right move for everyone. Your overall health, life expectancy and retirement tax situation should factor into the decision. While larger monthly checks are attractive, they could also increase the amount of your Social Security benefits that become taxable, depending on your total retirement income.

For those looking for some guidance, consider joining senior-focused organizations like AARP.

AARP members get access to guides that can help you make the most of Social Security, choose the right Medicare plan and uncover other government benefits — potentially saving you thousands.

As one of the most trusted organizations for older Americans, AARP not only helps you make informed financial and health decisions but also offers discounts on almost everything — from prescriptions and dental plans to travel, entertainment and insurance.

Sign up with AARP today and get 25% off your first year.

If an unexpected layoff happens just months before retirement, replacing even part of your lost paycheck can make a meaningful difference. Creating passive income ahead of retirement can help soften that blow, reducing your dependence on a single paycheck and giving you more flexibility over when you actually retire.

Real estate has long been one of the most popular ways to generate passive income. Rental properties can provide consistent monthly cash flow while offering the potential for long-term appreciation. But owning property outright isn't exactly a hands-off strategy.

Between mortgage payments, maintenance costs, property taxes and late-night calls from tenants, being a landlord can quickly turn into a second job — exactly what you might hope to avoid in your golden years.

Crowdfunding platforms like Arrived allow you to invest in shares of vacation and rental properties across the country with as little as $100.

Backed by world-class investors like Jeff Bezos, Arrived's team handles all the necessary work — from securing properties to finding and managing tenants — so you can sit back and become a landlord without having to do any legwork.

Arrived distributes any rental income generated by properties to investors monthly, allowing you to potentially set up a passive income stream without the extra work that comes with being a landlord of your own rental property.

The best part? For a limited time, when you open an account and add $1,000 or more, Arrived will credit your account with a 1% match.

If directly investing in rental properties feels like more commitment than you're looking for, income-focused real estate funds may offer a simpler alternative.

The Arrived Real Estate Income Fund is designed to generate regular dividend income while focusing on capital preservation.

The fund manages more than $83 million in assets and has historically delivered an annualized cash yield of more than 8.1%. To put this in perspective, even the "aristocrats" of dividend stocks struggle to reach a high-water mark of 5.51%, according to Morningstar (11).

How it works is simple: Arrived offers short-term loans for professional real estate projects seeking to renovate, refinance or fund new construction. Each loan goes through a disciplined selection process and is backed by residential real estate, adding another layer of underwriting rigor and downside protection.

Even better, Arrived Real Estate Income Fund investors also have quarterly liquidity options beginning six months after their initial investment, offering more flexibility than many traditional income-focused investments.

Here are the 7 top habits of 'quietly wealthy' Americans. How many do you follow?

'Gold still crashing!': Robert Kiyosaki admits he was wrong — but doubles down on his $35K prediction

When he dies, Warren Buffett said 90% of his wife's inheritance will go into a single investment. Here's why (and how you can do it too)

Are you paying too much for car insurance? Here are 3 clever ways to slash your monthly bill

Join 250,000+ readers and get Moneywise's best stories and exclusive interviews first — clear insights curated and delivered weekly. Subscribe now.

— With files from Emma Caplan-Fisher

We rely only on vetted sources and credible third-party reporting. For details, see our editorial ethics and guidelines.

Employee Benefit Research Institute (1); Society of Actuaries Research Institute (2); TheStreet (3); Medicare.gov (4); USA Today (5); Empower (6); Fidelity (7); Internal Revenue Service (8); Omny Studio (9); Social Security Administration (10); Morningstar (11)

This article provides information only and should not be construed as advice. It is provided without warranty of any kind.
Comments
You must be logged in to comment.