yahoo Press
Couple raising 4 kids admit they don’t track their purchases ‘unless it bounces.’ Here's how they can turn it around
Images
1 / 4
2 / 4
3 / 4
4 / 4
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.

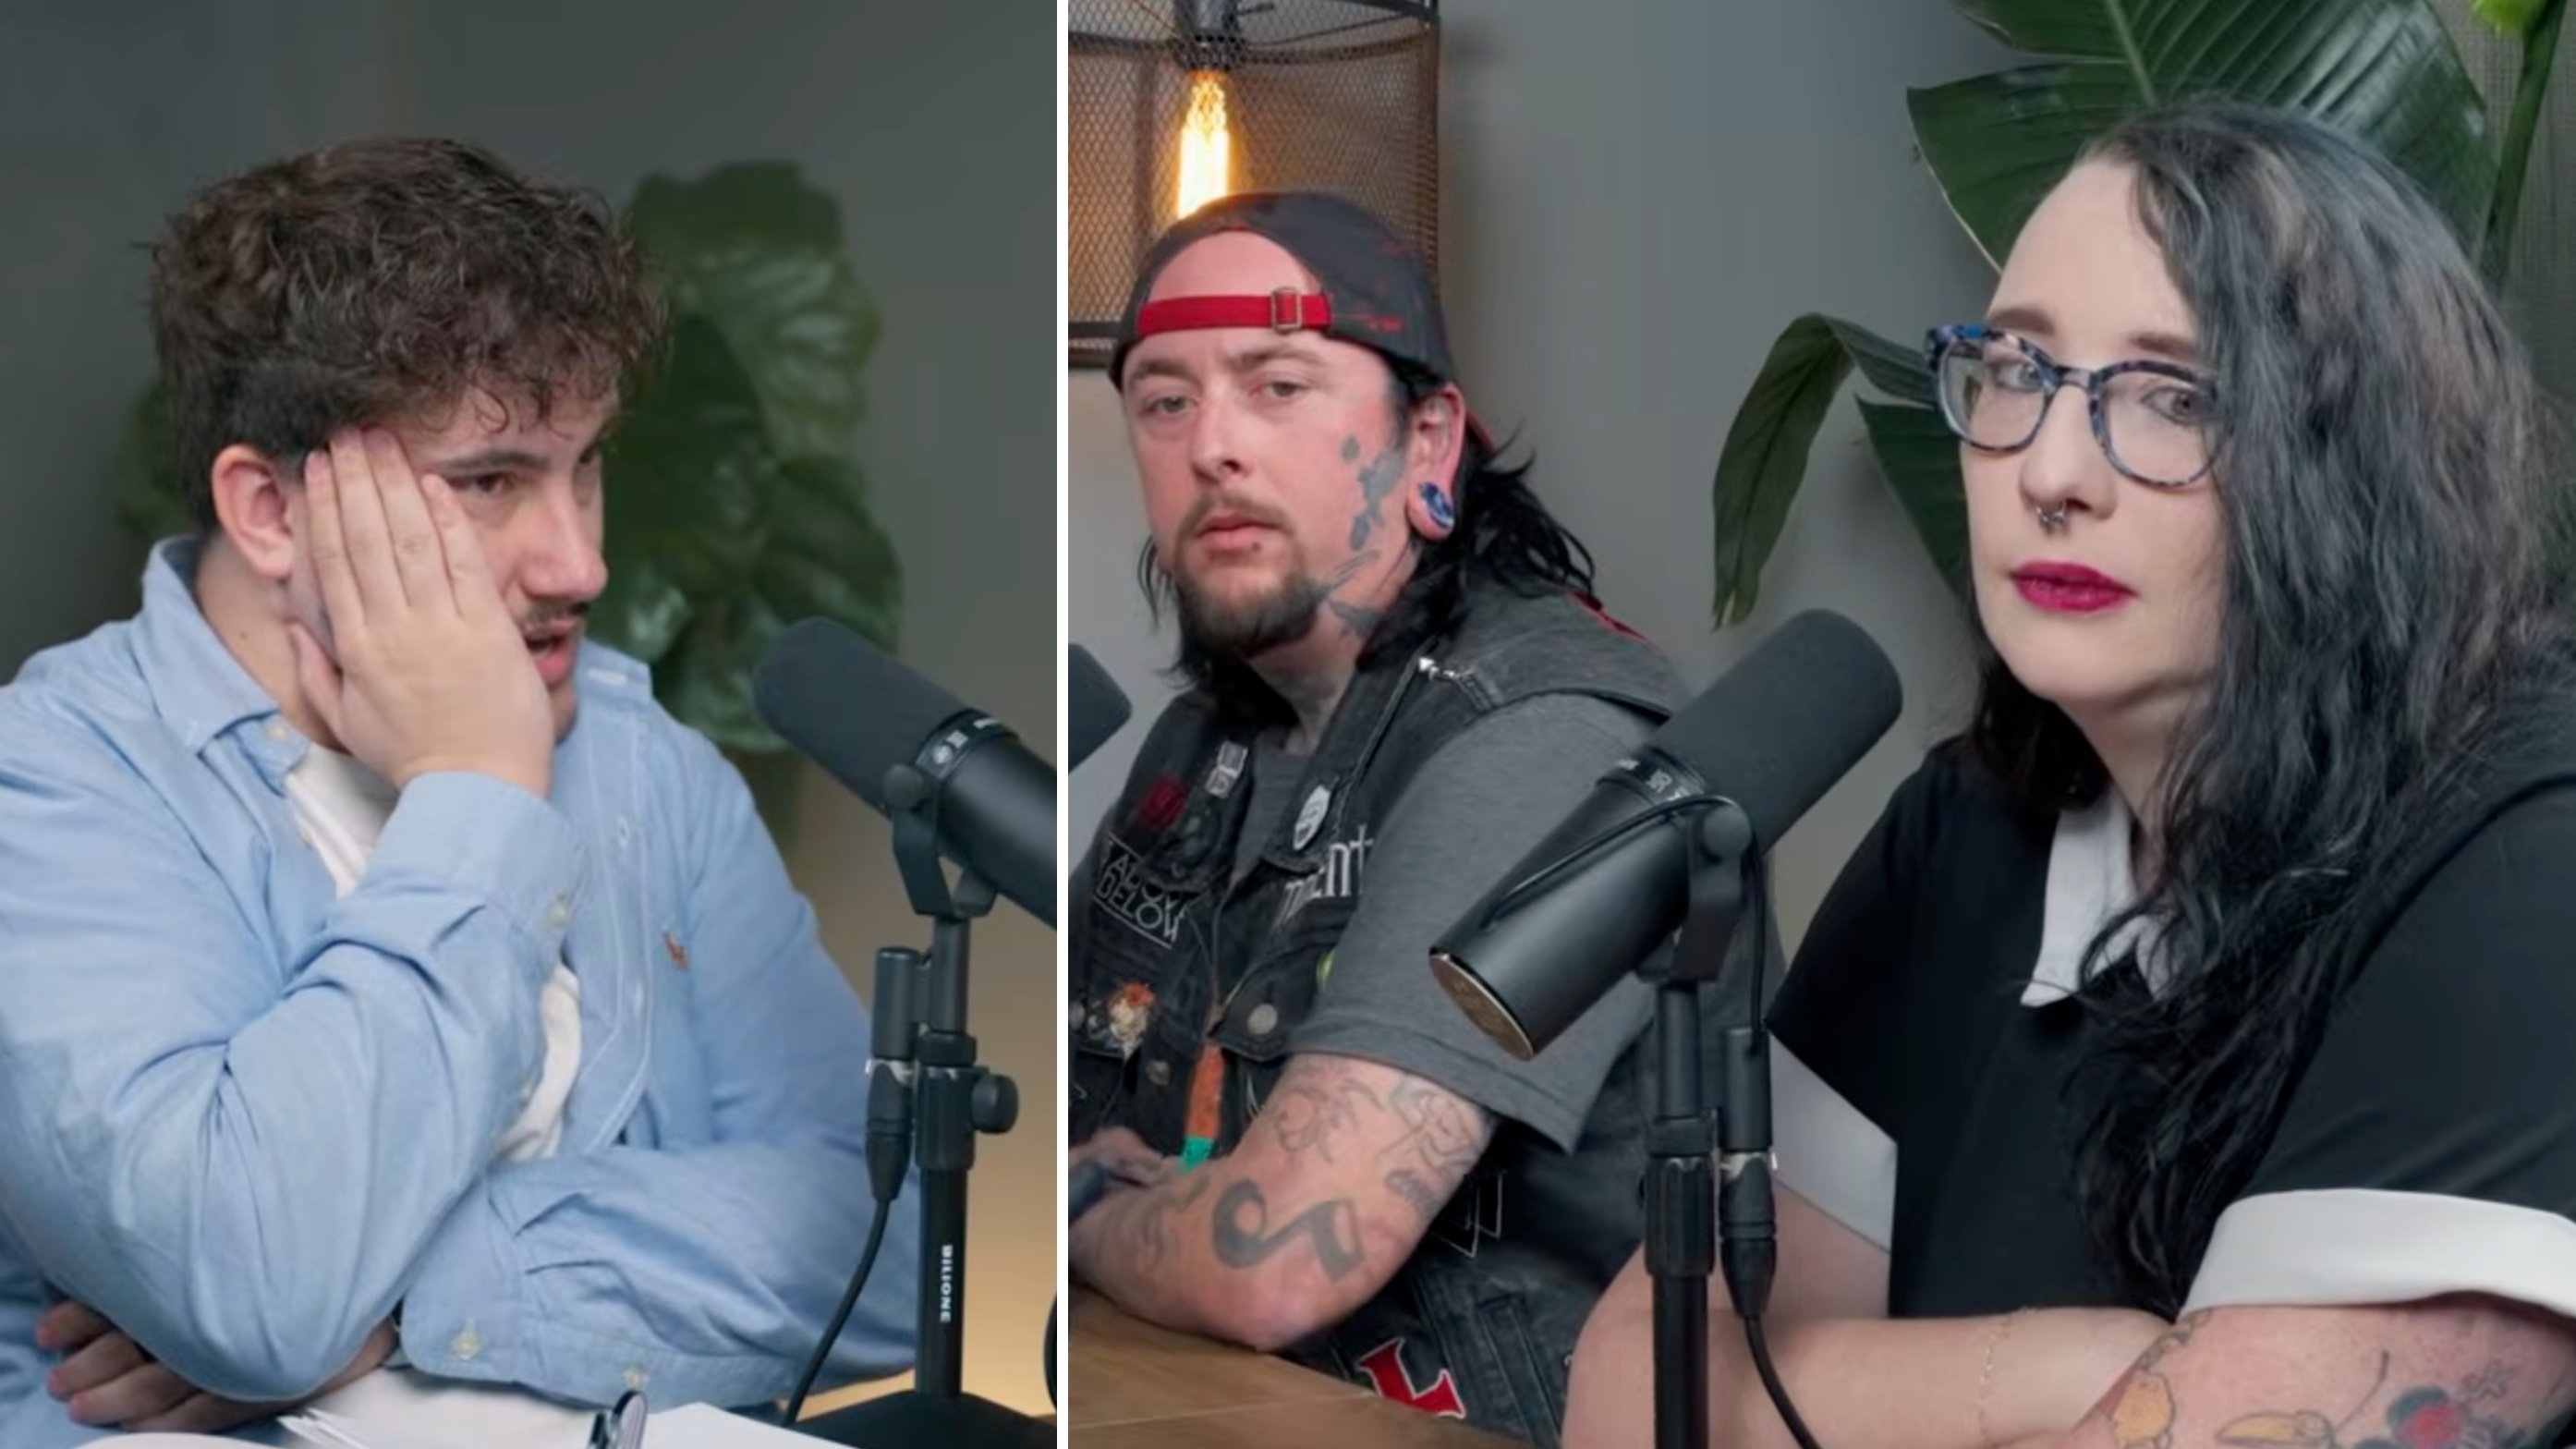
A young California couple, Emma and Brian, appeared on Caleb Hammer's Financial Audit podcast and admitted something that may be shocking to most viewers.

"I'm going to be honest with you, I don't look at the account unless it bounces," Emma said during the episode (1).

Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one

JP Morgan sees gold hitting $6,000/oz before 2027 — and a gold IRA lets you hold the physical metal while deferring the tax bill. Get your free guide from Priority Gold

The tax breaks in Trump's 'big beautiful bill' expire after 2028 — and experts say most people won't act in time. What to do before the window closes

Emma and her fiancé Brian live on the same property as her ex-husband, share financial responsibilities across households and are raising four children — all while struggling with mounting debt. This complex family situation masks a simple truth, their expenses are untracked and out of control.

Brian admitted his spending habits haven't helped.

"A lot of the times I just won't care … I'll go out to eat every day when I'm at work and I'll order on Amazon all the time," he said.

That combination, financial blind spots and impulse spending, has left the couple drowning in debt while raising four children.

Brian admitted that he rarely checks the accounts.

"I just don't look at the bank account," he told Hammer. "I just want to spend the money even though I can't."

Emma said the situation isn't much better on her side, "There is no organization, I'll be honest."

Financial avoidance is extremely common among couples dealing with stress or debt. Brian and Emma aren't alone on this strong — almost half (46%) of Gen Z adults avoid checking their bank account balances, according to a U.S. Bank survey (2). Meanwhile, a Capital One survey (3) found that 52% of Americans have trouble controlling their concerns over cash. Money matters also led to relationship strain among one-in-four respondents, although this could include family members — not just couples.

Ultimately, neither Brian not Emma took ownership of the numbers, small spending habits quietly spiralled into major financial problems for the couple.

And while they're certainly not alone in their financial predicament, small tweaks to mindset and approach could have kept them out of trouble — and can even now help them set their finances straight.

A quick daily check-in of your accounts can show you exactly where your money is going.

An app like Rocket Money can easily flag recurring subscriptions, upcoming bills and unusual charges by pulling in transactions from all your linked accounts.

This can help you cut unnecessary costs, and then you can manually redirect savings straight into your retirement fund. No spreadsheets, no guesswork, no stress. Small habits like this can make a big difference over time.

Rocket Money's intuitive app offers a variety of free and premium tools. Free features include subscription tracking, bill reminders and budgeting basics, while premium features — like automated savings, net worth tracking, customizable dashboards and more — make it easier to stay on top of your retirement contributions and overall financial goals.

But budgeting is only the first step towards financial freedom. And in Brian and Emma's case they have an equally big problem to tackle, that could eat up any gains from good budgeting — at least for a while.

Read More: Millionaires under 43 hold only 25% of their wealth in stocks. Here's where their money is actually going

The couple's spending habits snowballed quickly into debt. They financed everything from travel to food purchases using "buy now, pay later" (BNPL) plans.

At one point, they admitted they had dozens of active installment payments.

"You have 40 to 60 current paying for currently. Colton's telling me more than that," Caleb noted.

Even after tapping Emma's retirement savings to pay down debt, the cycle continued.

She added, "We paid off a car… and then we racked them up further than they were."

This is a common trap with BNPL services.

Each purchase may seem manageable — a $40 payment here or a $25 installment there. But when dozens of payments pile up at once, the total monthly obligation can balloon into hundreds or even thousands of dollars.

Installment services can create the illusion of affordability, encouraging consumers to spend money they wouldn't otherwise pay up front. Research from Harvard Business School found that BNPL adoption led to "immediate and substantial increases in spending," with the likelihood of making excess purchases increasing from 17% to 26% (4). Shoppers spent about 10% more per purchase on average after BNPL.

This dynamic escalates quickly. Imagine someone finances just 10 purchases at $200 each using a typical four-payment plan. Each purchase may only require $50 every two weeks, which feels manageable on its own.

But if all 10 purchases overlap, that person suddenly owes $500 every two weeks, or about $1,000 a month. And that's without factoring in the cost of borrowing — the interest rate of the loan itself.

When debt spirals out of control, some households use a strategy of consolidating balances into a single, lower-interest loan.

Credible is an effective tool to help get rid of your debt faster using just one predictable payment to manage each month.

Through Credible's online marketplace, finding the right loan becomes much simpler. Credible lets you comparison-shop for the lowest interest rates with just a few clicks.

In less than three minutes, you'll see all the lenders willing to help pay off your credit cards or other debts with a single personal loan.

If you owe a substantial amount, you may also want to see if you qualify for a debt relief program to help clear a significant portion of your debt.

With Freedom Debt Relief, you can speak with a certified debt relief consultant for free who can show you how much you may be able to save.

If you're eligible, they can negotiate settlements with creditors until your enrolled debt is resolved.

Money problems often extend far beyond the bank account.

In the podcast, Emma admitted she has grown frustrated with Brian's passive attitude toward finances: "I feel like he doesn't [care] … he's just there."

She confessed to feeling a built-up sense of resentment over the financial situation and Brian's lack of care for their shared obligations.

On the other side of this, Brian shared his frustrations that he wasn't being heard. He told Hammer, "A lot of the time the outcome I want won't happen." But, clearly, complacency hasn't served the couple either.

Financial disagreements are one of the most common sources of stress in relationships.

According to research published in the National Library of Medicine, 40% of disagreements in long-term relationships involve finances (5).

Additionally, an Ipsos poll found that one in three American couples view money as a source of conflict in their relationship (6). This figure rises to almost half of the youngest partnered Americans (18–24-year-olds). In the same study, couples admitted to being untruthful about their money with their spouses in 36% of cases.

When couples don't agree on priorities, whether it's spending, saving or career decisions, money problems can quickly become personal conflicts.

For couples dealing with complicated finances, a neutral third party can sometimes help.

Financial advisors can help households create a realistic plan for managing debt, building savings and planning for the future.

Advisor.com does the heavy lifting for you, vetting advisors based on track record, client ratios and regulatory background. Their network is made up of fiduciaries who are legally required to act in your best interests.

Just enter a few details about your finances and goals and Advisor.com's AI-powered matching tool will connect you with a qualified expert based on your situation.

You can even schedule a free initial consultation with no obligation to hire, helping you determine whether the advisor is a right fit.

Early on during the podcast, Hammer pointed out that financial tools and resources are more accessible than ever: "You have access to every resource that existed in the history of the world."

For couples in similar situations, these are a few basic steps that can make a huge difference. To summarize, the couple could:

Track spending and build a realistic budget

Stop relying on buy-now-pay-later plans

Build an emergency fund to avoid future debt

Consolidate high-interest balances

Look for ways to increase income over time

Even small improvements can start reversing a cycle of debt. And once you're out of the debt spiral, it's a lot easier to build substantial wealth.

Even small investments can grow significantly over time thanks to compounding.

For example, investing just $5 a day (roughly the cost of a coffee) would add up to about $150 a month. If that money were invested and earned an average annual return of 7%, it could grow to more than $180,000 after 30 years.

That's the power of starting small and staying consistent.

And Even small amounts can grow over time with tools like Acorns, a popular app that automatically invests your spare change. Once Brian and Emma are out the other side, it's time to starting saving, and building those habits with an automatic service could be a good place to start.

Signing up takes just minutes: Just link your cards and Acorns will round up each purchase to the nearest dollar and invest the difference into a diversified portfolio. Remember that coffee? It could now be an investment in your future.

With Acorns, you can start investing with as little as $5 — and if you sign up today, Acorns will add a $20 bonus to help kickstart your investment journey. Investors can get started by setting up a recurring investment of at least $5.

'Gold still crashing!': Robert Kiyosaki admits he was wrong — but doubles down on his $35K prediction

I'm 49 years old and have nothing saved for retirement. What do I do? Don't panic. Here are 7 ways to catch up fast

When he dies, Warren Buffett said 90% of his wife's inheritance will go into a single investment. Here's why (and how you can do it too)

Are you paying too much for car insurance? Here are 3 clever ways to slash your monthly bill

Join 250,000+ readers and get Moneywise's best stories and exclusive interviews first — clear insights curated and delivered weekly. Subscribe now.

We rely only on vetted sources and credible third-party reporting. For details, see our ethics and guidelines.

Caleb Hammer/ YouTube (1); U.S. Bank (2); Capital One (3); Harvard Business Review (4); National Library of Medicine (5); Ipsos (6)

This article provides information only and should not be construed as advice. It is provided without warranty of any kind.
Comments
You must be logged in to comment.