yahoo Press
My mom, 74, fell for a phone scam — and now I'm out $12,000 because our bank accounts are linked. What can I do?
Images
1 / 4
2 / 4
3 / 4
4 / 4
Americans lost a shocking $3.5 billion to imposter scams in 2025, according to data from the Federal Trade Commission (1). These losses are around three times greater than in 2020. Imposter scams were the leading cause of fraud last year, with almost one in three fraud reports related to scammers impersonating others via phone, text, or other means.

Imposter scams involve a criminal pretending to be someone they're not, like a bank rep or government official, to convince the victim to give them money or personal details. These scams often target older Americans (2), but it's not just seniors who pay the price. Young people can find themselves facing financial losses too — in some cases because they tried to help a parent.

Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one

Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake — here's what it is and 3 simple steps to fix it ASAP

Millionaires under 43 hold only 25% of their wealth in stocks. Here's where their money is actually going

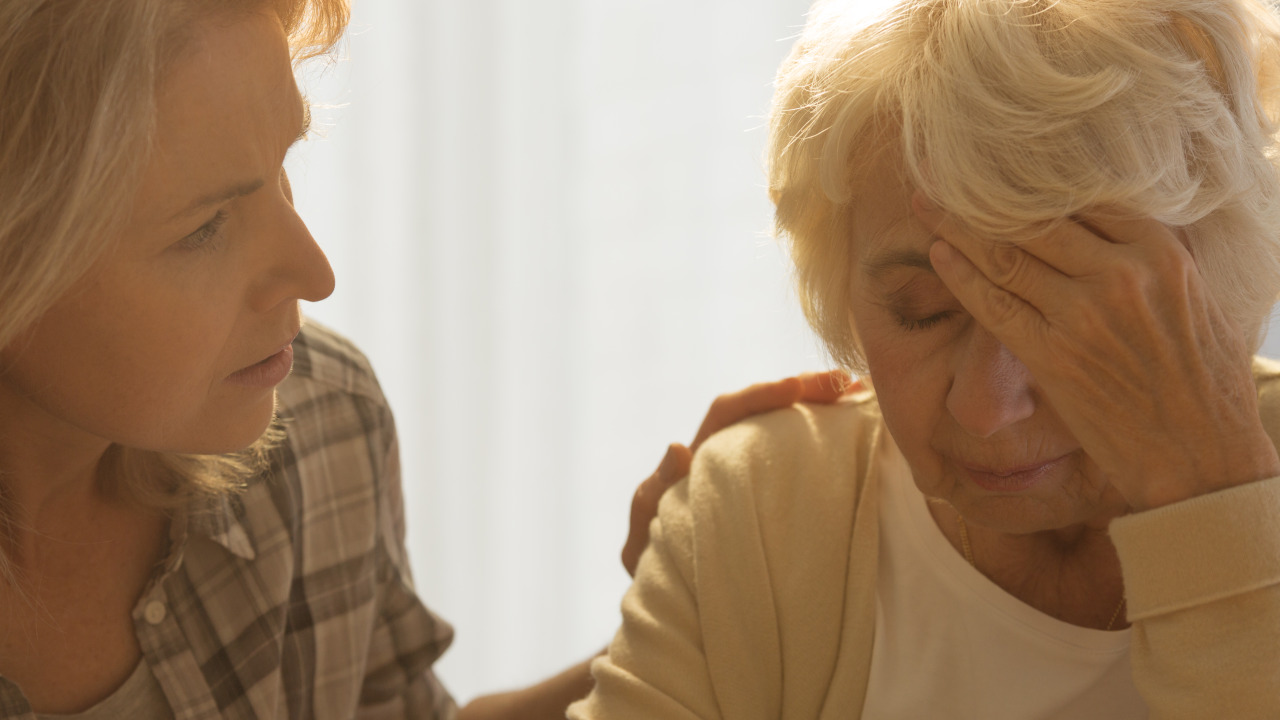
Let's pretend, for example, that Rebecca has her bank account linked to her mother's in case she needs access to it in the event of a death. Unfortunately, Rebecca's mom, Sally, fell victim to a phone scam and wired $12,000 to a criminal pretending to be an FBI official trying to stop bank fraud.

Since Sally didn't have enough money in her own account to transfer the $12K, the teller asked Sally if she should use Rebecca's linked account, and Sally agreed. Now, Rebecca is out the $12,000 and is concerned about her mom potentially making a similar mistake in the future. She's wondering if she has any options.

Rebecca's first concern is whether she can recover her money, but experts say that's not likely.

"Unfortunately, recovery is not guaranteed after victims have fallen victim to phone scams," Katherine A. Kiziah (3), a lawyer and partner at Rafferty Domnick Cunningham & Yaffa, told MoneyWise. "The perpetrators of these scams are often outside of the United States. Even within the USA, we are dealing with criminals who immediately spend or move money."

Kiziah explained that acting very quickly is crucial when trying to get any lost funds back.

"The best chance for recovery is with the financial institution or company through which money was transferred. And immediate action is necessary. Every day that goes by reduces the chance of recovery," she said.

Kiziah recommends reaching out to the fraud department of the bank, wire service, credit card company or app, as well as filing a police report and potentially talking with a lawyer to determine if there are any avenues for recovery. While this may not guarantee success, at least it gives Rebecca some options.

Rebecca should also take immediate steps to try to prevent further damage if her mom provided sensitive, personal information.

"Place a credit freeze on your credit accounts with Experian, Equifax and TransUnion," Danny Karon (4), a consumer attorney, law instructor and owner of Karon LLC, recommended to MoneyWise. "That will prevent fraudsters from opening credit accounts in your name for things such as cars and homes."

Read More: Are you paying too much for car insurance? Here are 3 clever ways to slash your monthly bill

Rebecca also has another big issue to deal with beyond her lost $12,000. Since her mom has already fallen victim to one scam, there's a chance it could happen again. And Rebecca needs to take steps to prevent that so her mom doesn't make another costly error.

"Having difficult conversations about finances is hard for elderly parents and their adult children," Patty Laychock (5), a Certified Senior Advisor (CSA) and owner of Visiting Angels Senior Home Care, told MoneyWise. "Don't place blame on your elderly parents for being the victim of scams. Approach the conversations as a partnership designed to protect their wishes and plans for retirement. Be empathetic, patient and compassionate."

Laychock suggested Rebecca talk to her mom "early in the day or after a meal, when elderly adults are the most clear-headed," and that Rebecca "maintain eye contact and use short, simple sentences" to discuss the issue.

Rebecca should urge her mother not to answer unfamiliar numbers and never to give money or personal details to anyone based on an unsolicited call.

Lastly, Laychock advised that Rebecca may also want to get a durable power of attorney to manage Sally's accounts, automate bills to limit the financial transactions Sally needs to take part in, set up bank alerts to monitor for unusual withdrawal activity and limit withdrawal amounts.

Rebecca also needs to separate her bank account from her mother's so her own finances are not affected further.

"Because scammers use tactics to trick victims into initiating real payments or providing account credentials, linking accounts would provide the scammer with direct access to the combined funds," Graphika (6) intelligence specialist Angie Waller told MoneyWise.

"If a parent is identified as prone to falling victim to scams, they are often targeted repeatedly. Providing access to joint accounts extends the potential reach of these fraud operations to any funds or assets connected to those accounts," Waller warned.

Rebecca should take Laychock's suggestions and monitor her mother's account while setting up limits, rather than co-mingle their funds directly. If she's worried about accessing her account upon a sudden death, other tools like a pay-on-death designation (7) are a better bet.

Hopefully, Rebecca can help Sally learn to avoid scams going forward. But regardless, Rebecca must make sure her personal assets aren't at risk anymore, as she's already likely lost $12,000 for good.

'Gold still crashing!': Robert Kiyosaki admits he was wrong — but doubles down on his $35K prediction

The tax breaks in Trump's 'big beautiful bill' expire after 2028 — and experts say most people won't act in time. What to do before the window closes

Here's the average income of Americans by age in 2026. Are you keeping up or falling behind?

When he dies, Warren Buffett said 90% of his wife's inheritance will go into a single investment. Here's why (and how you can do it too)

Join 250,000+ readers and get Moneywise's best stories and exclusive interviews first — clear insights curated and delivered weekly. Subscribe now.

We rely only on vetted sources and credible third-party reporting. For details, see our ethics and guidelines.

Federal Trade Commission (1); U.S. Department of Justice (2); PBG Law (3); Your Lovable Lawyer (4); Visiting Angels (5); Graphika (6); Experian (7)

This article originally appeared on Moneywise.com under the title: My mom, 74, fell for a phone scam — and now I'm out $12,000 because our bank accounts are linked. What can I do?

This article provides information only and should not be construed as advice. It is provided without warranty of any kind.
Comments
You must be logged in to comment.