yahoo Press
Current balance vs. available balance: What's the difference?
Images
1 / 11
2 / 11
3 / 11

4 / 11
5 / 11
6 / 11
7 / 11
8 / 11
9 / 11
10 / 11
11 / 11
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.

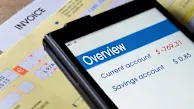
If you've ever looked to see how much money is in your checking account, you've probably noticed something confusing: You have two different balances for one account.

Banks show you both your "current balance" and your "available balance." But one of these figures gives you a more accurate picture of how much money you have available to spend. So what's the difference between these two numbers, and which one should you pay attention to?

When you make a deposit or purchase, it can take a few days for the bank to process the transaction and transfer the money in or out of your account. To help you avoid spending money that's already on its way out, the bank shows you both your current balance and your available balance. Here's how the two figures differ:

Current balance: Your current account balance only includes transactions that have fully cleared. It does not include debits or credits that are pending. Due to processing delays, this figure may not reflect transactions that were initiated in the previous one to three business days.

Available balance: Your available account balance includes all of the pending credits and debits that your bank is aware of. In other words, it represents that total balance available to spend without overdrafting.

If you want to see a breakdown of your pending transactions so you can understand why your current and available balances differ, you can usually see them listed at the top of your account transaction history.

The main reason your available balance and current balance are different is due to the processing speed of transactions.

Depending on the type of transaction, it could take anywhere from a few seconds to several business days for a purchase or a deposit to be processed, also known as "settling" or "clearing." But while the transaction is being processed, the debit or credit won't impact your current balance; it will only impact your available balance.

Here are some common reasons the available and current balance are different:

You made a debit card purchase that hasn't been fully processed by your bank.

You wrote or deposited a check that hasn't cleared yet.

You have an upcoming automatic payment that you pre-authorized for a recurring bill.

You recently transferred money from your bank account to a payment app like PayPal.

The amount of time it takes for your current balance and available balance to reconcile depends on the type of transaction. Here's how long these common transactions take:

FedNow (bank to bank): Instantly

Zelle: Minutes

Payroll direct deposit: Up to 1 business day

Credit and debit cards: 1-2 business days

Check deposit: 1-2 business days

Automated Clearing House (ACH): 1-3 business days

Bank to Venmo: 1-3 business days

Bank to Paypal: 3-5 business days

Your available balance is typically the most accurate figure to go by since it takes your pending transactions into account. Using this figure will prevent you from spending money that's already due to be withdrawn.

Spending your full available balance is still a risk, however, since it can reflect a credit that later gets rejected. For example, if you deposit a bad check, there's a chance you'll see the credit reflected in your available balance before the check bounces. And if you write a check, the check amount won't be reflected in your available balance at all until it's deposited by the recipient.

To avoid spending money you don't have in your bank account — also known as overdrafting — try following these tips:

Manually calculate your balance: Subtract your recent and upcoming bill payments, plus any checks you've written, from your available balance in order to get a better estimate of your available funds.

Don't spend in advance: Don't spend money from a deposit to your account until the transaction clears.

Keep a cushion in the account: Keep extra funds in your checking account that you never plan to spend, perhaps $100 to $1,000. That "cushion" will help you avoid overdrafting if you mistakenly assume you have extra funds available.

Avoid using checks. Speed up your transactions by using electronic payments instead of checks. For your paycheck, set up direct deposit.

Cancel overdraft protection: If you have overdraft protection and your account goes negative, the bank will automatically loan you money to cover the transaction and charge you a fee around $35. But if you don't have overdraft protection, debit transactions will simply be declined. For checks, you might be charged a non-sufficient funds (NSF) fee.

Your available balance is likely less than your current balance because you have one or more pending transactions. Once your purchases or bill payments go through, your current balance will be updated to reflect the transaction.

Your present balance, more often referred to as your current balance, only includes transactions that have fully cleared, while your available balance shows debits and credits that are still being processed.

With so many checking accounts to choose from, how do you know which one is the best? That’s the topic of this week’s Reddit thread. We’ll break it down for you.

You probably know you shouldn’t overdraft your bank accounts, but what does that mean exactly? And how can you avoid overdraft fees? Here’s what you should know.

Dealing with your finances can feel cumbersome at times, but taking a proactive approach to managing your money can save you quite a bit of money. Here are five costly mistakes to avoid.

Current is a financial technology company that offers innovative banking and credit-building products. Should you bank with Current? Find out with this in-depth review.

Choosing between a money market or checking account depends on your goals and preferences. Learn how money market vs. checking accounts compare, and which one is right for you.

Knowing the average checking account balance in the U.S. can help you assess your own financial health. Here’s a look at the average checking account balance and how to increase yours.
Comments
You must be logged in to comment.